Selling a house in a flood zone in Navarre FL is completely doable. Thousands of owners do it every year along the Gulf Coast. The trick is knowing what buyers and lenders will ask before you list.
Navarre sits between Pensacola and Destin on Santa Rosa County’s coast. It is a beautiful place to live. The beaches draw people in. The catch is that much of the area sits in a flood hazard area mapped by FEMA. That one fact changes how your home gets priced, financed, and insured.
A quick answer to an important question. Buyers need assurance that the house is safe and insurable. Lenders need assurance that their loan is insured. You provide those two assurances, and the house sells. Don’t hide anything, and the sale falls through during inspection.
Let us get you ready.
How Other Blogs Cover This Topic and Where They Fall Short
Before we dig in, let us look at what the top-ranking pages already do. Most articles on selling property in a FEMA flood zone Florida follow the same pattern. They define zones, mention insurance, and add a generic checklist. A few stand out.
The major insurance websites have everything regarding flood zones. They define AE and VE zones in a clear tabular format. However, their weakness is in terms of local specifics. These websites do not mention anything about Santa Rosa County Flood Maps and storm surge effects on Navarre coastlines.
The national real estate blogs talk about disclosure and appraisals. However, their weakness is on cost realities. They give national averages which do not reflect the prices of Gulf Coast property market. The wind and flood premium costs in Navarre are significantly above the national averages.
The investor sites cover only cash and as-is sales. However, their weakness is on balance. They give one method while others exist. Here, this blog covers all methods, so that you may choose according to your needs.
Selling a House in a Flood Zone Starts with the Map
Firstly, you should find your flood designation. You have to do it first and foremost because everything that follows will be contingent on this.
The official maps are maintained by the Federal Emergency Management Agency, which are named the flood insurance rate maps (FIRMs). You can find any location for free through the FEMA Map Service Center (msc.fema.gov).
Santa Rosa County also has its property look-up service. It combines flood information with parcel lines. This comes in handy if your property lies on the boundary of two zones. In case your lot falls in between two zones, then the riskier one is applied throughout the entire property.
How can this be significant? As FEMA states, a house located in a special flood hazard area has an approximate 26 percent likelihood of experiencing flooding over a 30-year period. This statistic may come as a shock to people.
And here is something else worth knowing. FEMA says 20 to 30 percent of NFIP claims come from outside the high-risk zones. Even X zone homes flood.
Explore Your Cash Home Selling Options
We buy houses in ANY CONDITION in Florida. There are no commissions or fees and no obligation whatsoever. Contact Quality Properties of Northwest Florida LLC
FEMA Flood Zone Designations Explained in Plain Words
Any zone starting with A or V is a special flood hazard area. These are high-risk flood areas with at least a 1 percent annual chance of flooding. If your buyer uses a federally backed loan, mandatory flood insurance kicks in.
| Zone | Risk Level | Insurance Rule | Typical NFIP Cost |
| AE | High risk, BFE published | Required with federal loan | $1,500 to $4,000 per year |
| A | High risk, no BFE | Required with federal loan | $2,000 to $5,000 per year |
| VE | Coastal, wave action | Required with federal loan | $4,000 to $12,000 per year |
| X shaded | Moderate risk | Not required | $500 to $800 per year |
| X unshaded | Minimal risk | Not required | $400 to $700 per year |
The costs above come from current Florida insurance planning data. Your real quote will vary. Elevation, distance to water, and prior claims all move the number.
What Buyers Look for When You Sell House in Flood Zone Navarre FL
Buyers in the Navarre FL flood zone real estate market ask smart questions now. Storm seasons made everyone sharper. Here is what they want.
- They want your elevation certificate. The elevation certificate tells them the elevation of your home’s lowest floor compared to the BFE. Building your home above the BFE means that you will pay less for insurance and the buyers will buy more quickly.
- They want your flood history. Any previous flood damage, water intrusion, or mold remediation work should be documented. Receipts matter. They want a home inspection and a wind mitigation inspection too.
- They also want to know about the drainage system, flood vents, and whether the home has a raised foundation. An elevated home with proper flood vents can earn lower premiums and a stronger property appraisal.
What Lenders Check Before Mortgage Approval
If the house is located in either an A zone or V zone and the purchaser has financing from the government, the lending company would need the home to have flood insurance coverage. No coverage results in no financing. This is mandatory under federal law.
The two items are considered together by the lenders when determining whether there will be mortgage approval. If it is a VE zone, there could be fewer potential buyers due to rising premiums.
The property appraisal matters here too. An appraiser checks comparable sales in the flood zone real estate market Navarre FL. If nearby elevated homes sold for more, your appraisal gets compared against them. A solid comparative market analysis helps your agent defend your price.
What Flood Insurance Really Costs in 2026
Florida holds about 1.77 million active NFIP policies. That is nearly 39 percent of every policy in the country.
The new system of FEMA’s Risk Rating 2.0 has affected the process of determining the premium. The pricing is dependent on the property rather than the zones. Elevation, water proximity, and replacement costs are considered in the calculation. Two houses located on the same street could have completely different premiums.
One last thing. If your purchaser can take over your NFIP policy at the time of closing, they retain your capped rate schedule. There is an annual increase cap of 18 percent for the vast majority of policies. Lapsing a policy could set it at a much higher premium.
A conventional homeowner’s insurance policy will not cover damage from a flood. Your purchaser must have their own flood insurance policy, either through NFIP or a private insurance company.
Coverage under the NFIP is limited to $250,000 for the building and $100,000 for the contents. Private flood insurance limits can be greater, but insurers can cancel policies following storm seasons.
Pricing Your Home and Protecting Home Equity
Begin with a comparative market analysis done by an agent familiar with Gulf Coast property market trends. Do a comparison between elevated and non-elevated houses. Factor in costs of insuring against floods. The buyer who pays $3,500 a year in flood insurance will pay less for the same property.
With proper preparation, you can retain your fair market value. Address the drainage problem first. Make sure you have estimates for fixing other problems. Remove molds that may have accumulated in case there were floods in the past. It is better to do some spending now than to make cuts in the future.
Repairs and Flood Mitigation That Pay You Back
Renovation is not required to solve your problem.
Targeted flood protection is where you will see results. Flood vents in the crawl space or garage reduce costs and demonstrate that the house breathes during the flood. A raised foundation or elevated home is ideal but expensive – but makes all the difference to insurability.
Grade work can ensure the water flows away from the house. Gutters must be cleaned and downspouts extended. The damage to the foundation due to previous storms needs to be addressed and recorded.
A wind mitigation inspection can cut the wind portion of the buyer’s insurance bill. Pair that with your elevation certificate and you hand the buyer a savings file. Sellers who do this close faster. I have seen it happen more times than I can count.
Selling a Flood Damaged House in Navarre FL
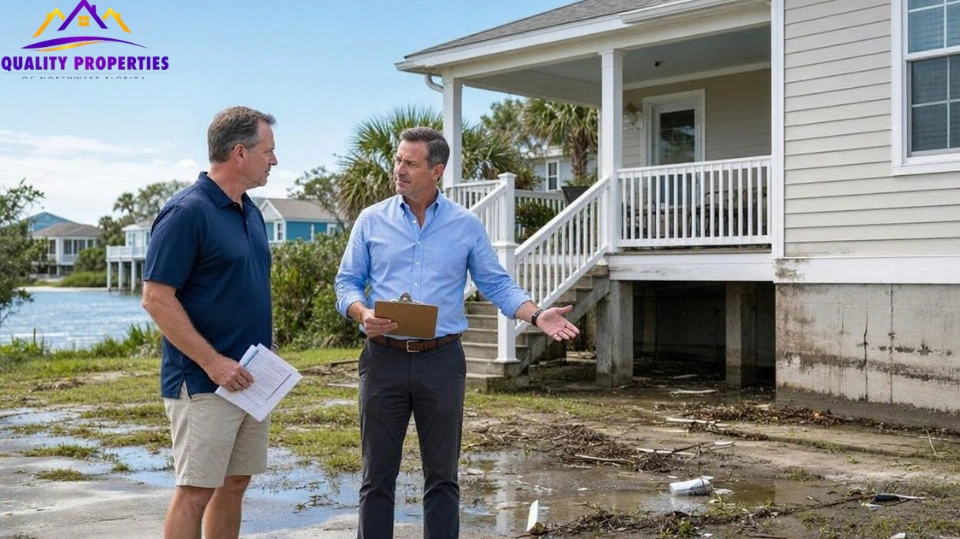
What if your home took real hurricane damage or heavy rainfall flooding? You still have paths forward.
The traditional route involves the complete repair of the damage done to the property, repairs to the structure itself, and the passing of a home inspection process. All this takes several months.
The faster route is to sell the as-is house to cash home buyers or investors in real estate. No repairs are needed, no appraisals, no delays caused by the lack of lender flood insurance. The average payout for an NFIP claim in Florida in the last ten years was around $28,100, and the restoration usually ends up costing much more.
An off-market property sale can be completed in a few days. You receive the proceeds from the sale of the house without paying the agent’s commission, closing costs, and renovation expenses.
If you need to sell my house fast Navarre FL, Quality Properties of Northwest Florida LLC buys homes as-is across the Gulf Coast. One quick property closing, no repairs, no lender delays. Visit them to get a no-obligation cash offer.
Disclosures, Paperwork and the Title Company
In Florida, it is mandatory for sellers to disclose any known defects. These include past flood history, flood damage, and drainage problems. Make sure you complete the seller’s disclosure statement in full.
Your title company will perform the title search and transfer the title. They may ask you about previous claims and elevation certificates. Make sure you have all these in one place.
The purchase agreement should note the flood zone clearly. Serious buyers already know. Surprising them late kills trust and deals.
Common Mistakes When Selling Flood Zone Property Navarre Florida
- Hiding the history of flood damage is a critical error that will come to light. It happens with both buyers and lenders. Transactions fall apart, and lawsuits begin.
- A close second on the error list is overpricing versus insurance. A home priced at $400,000 that has a $8,000 annual VE premium will remain on the shelf. Potential buyers know math.
- The third error is not getting the elevation certificate. If you don’t, buyers will make their own assumptions. That could be costly for you.
- Waiting too long is the fourth mistake. Hurricane season makes or breaks Gulf Coast property. List all documents ready before the hurricane season starts.
Final Words
Selling a house in a flood zone in Navarre FL comes down to three things. Know your flood zone classification. Price for the cost of real insurance. Be completely forthcoming and prove the rest.
The buyers and the lenders all require the same documentation. The property is insurable, raised to the max and disclosed as such. Give them that and your Navarre Florida flood zone home sale will close without a problem.
Whether you list traditionally or take a direct cash route, preparation is what protects your home equity. If you want a no-pressure conversation about your options, Quality Properties of Northwest Florida LLC is happy to walk you through them.
Frequently Asked Questions
Is my Navarre house in a flood zone?
Go to msc.fema.gov and type in your address. The official flood map shows your zone instantly.
Does a flood zone make my house unsellable?
No. Navarre FL flood zone real estate sells every week. Pricing, elevation, and honest disclosure decide speed more than the zone itself.
How much does flood insurance cost in Navarre?
Most AE zone homes run $1,500 to $4,000 per year through NFIP. VE zone homes can reach $12,000 or more.
Can I sell house with flood insurance Navarre FL still active?
Yes. You can assign the policy to your buyer at closing. This keeps their rate on the capped increase path.
Do I have to fix flood damage before selling?
Not if you sell as-is. Selling a flood damaged house in Navarre FL to cash home buyers means no repairs and no inspection contingencies.
Will a lender approve a loan on a VE zone home?
Yes, if the buyer qualifies for the higher flood insurance premium and meets mortgage lender requirements.
How fast can a flood zone home sale close?
Traditional sales take 30 to 45 days. A cash offer through a direct property sale can close in as little as 7 to 14 days.
