There is no doubt foreclosure will impact you. Besides the obvious strain and emotional impact the situation can have on your family and personal relationships, foreclosure can also devastate your finances. From the clothes you wear to the car you drive, or even where you reside or work, it will have a residual effect on your life for years to come. Foreclosure may impact you, but you can be certain that Quality Properties Of Northwest Florida LLC is here for you!
We’re here to listen to you and can address any questions you may have about your specific circumstances and what you can do to avoid these ramifications. Just call 850-346-4995.
By having a better understanding of what lies ahead, you will be better equipped for taking immediate action against the negative consequences of foreclosure from the start.
Your future self will thank you for taking the time to learn more about your options during the process. We’ll cover 4 ways that a foreclosure will impact your credit, finances, debt, and future housing options in Pensacola.
4 Ways a Foreclosure Affects Your Credit, Finances, and Future in Pensacola
1. Denied Credit and Loan Applications
Having a foreclosure in Pensacola appear on your credit reports will cause you to be considered a bad risk. Once this appears in your credit history, it will impact your overall purchasing power. Bad credit often leads to credit applications being denied for credit cards, loans or mortgages. Any financial institution that is willing to approve consumers with bad credit usually charges exorbitant interest and annual fees that those who enjoy good credit avoid. Additionally, it could possibly be a reason you are passed over for employment opportunities.
A foreclosure on your credit history can follow you in a few different ways:
- Higher interest rates and fees on any credit you’re still approved for
- Denied applications for credit cards, auto loans, or a new mortgage
- Some employers running credit checks as part of hiring decisions
2. Financial Loss From Lost Home Equity
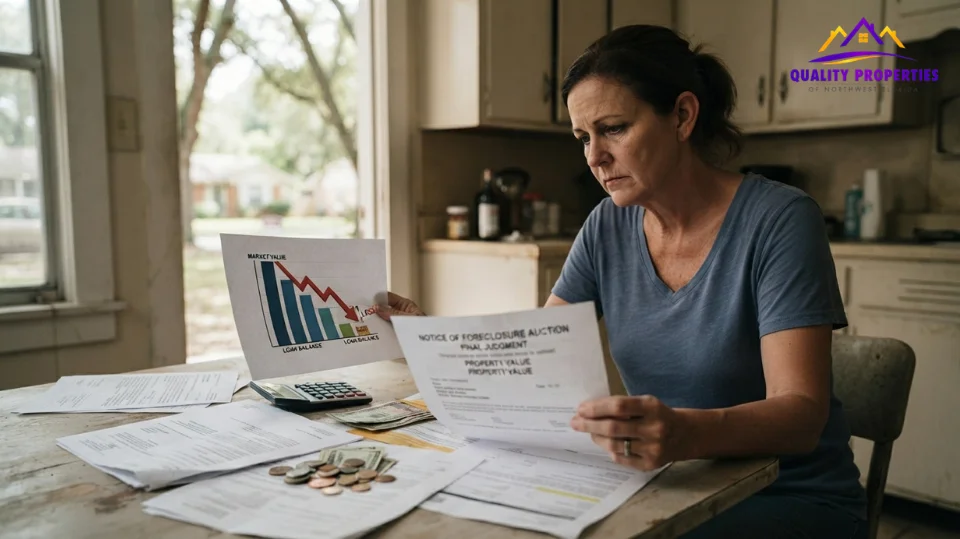
Among the top reasons for homeownership, your equity builds up over time as your debt decreases, and Pensacola property values rise. Your financial gains could be an amount in the hundreds of thousands. Equity is the difference between what your property would bring in the current market, and the amount that is still owed on the mortgage. Depending on your circumstances, a foreclosure will impact your equity either partially or in full, which could be a significant financial loss.
3. Deficiency Debt You Could Still Owe
By taking quick steps to resolve a pending foreclosure, you can make the decisions on how your home is sold and for how much. Open your mail before it’s too late! Keep the lines of communication open so that you can be on top of what actions your lender may be ready to take and how much time you have to change the outcome in your favor.
After a foreclosure you’ll have no such control. Should your Pensacola property sell for less than is still due on your mortgage, you will still be required to make payments on this debt. This is known as a deficiency debt and can have an enormous impact on your lifestyle and family. Not to mention eating into your budget. Additional liability on your credit report will only increase the higher costs associated with having bad credit.
4. Future Housing and Mortgage Eligibility
Foreclosure impacts your housing options in many ways. In general, landlords run credit checks as the first step when interviewing tenants. Naturally, your financial history will make you a higher risk and may cause you to be passed over for more desirable properties.
Additionally, your choices in financing will be highly restricted should you wish to purchase another home. Fannie Mae is among the largest in the nation and offers a program with several financial benefits. Should you have gone through foreclosure and seek a mortgage lender, you should be aware that Fannie Mae generally requires a seven-year waiting period before you will be eligible under their guidelines, though this can sometimes be shortened with documented extenuating circumstances.
Final Thoughts: Don’t Face Foreclosure in Pensacola Alone
Facing the possibilities of a Pensacola foreclosure alone can be very stressful, and inaction on your part risks your financial future. A foreclosure can follow you for years, affecting your credit, your ability to borrow, and even where you can rent or buy next. Understanding these risks early gives you more options and more time to protect what you’ve worked for.
If your home is heading toward foreclosure, comparing your options including selling a foreclosure property in Pensacola for cash could help you avoid many of the consequences above. Don’t wait until foreclosure begins let Quality Properties Of Northwest Florida LLC help lessen your burdens today. Send us a message or give us a call today at 850-346-4995.
Frequently Asked Questions About Foreclosure in Pensacola
How long does a foreclosure stay on your credit report?
A foreclosure can remain on your credit report for up to seven years from the date it was recorded, even after you’ve rebuilt your finances.
Can I sell my house during foreclosure in Pensacola?
Yes. Homeowners can often sell before the foreclosure process completes, which may help you avoid a deficiency debt and further credit damage. Comparing cash buyers vs. realtors during foreclosure in Pensacola can help you decide which route fits your timeline.
What is a deficiency judgment in Florida?
It’s the difference between what you owe on your mortgage and the amount your home sells for at a foreclosure auction. In Florida, lenders can pursue the remaining balance from the homeowner.
How long do I have to wait to qualify for a mortgage after foreclosure?
Under standard Fannie Mae guidelines, most borrowers must wait around seven years, though documented extenuating circumstances may shorten that waiting period.
Is foreclosure the same as bankruptcy?
No. Foreclosure is the loss of a specific property to your mortgage lender, while bankruptcy is a broader legal process for resolving overall debt. Either one, however, can significantly affect your credit and financial future.
